Ena Thatcher was 71 when she became a mortgage co-signer on her son’s $400,000 home loan. Two days later, she spotted forty cream-colored invitations on his new kitchen island, and not one carried her name. What she did next led to an unforgettable night on a lakeside dock in front of 58 guests.
What a Mortgage Co-Signer Actually Signs
The closing took place on Thursday, August 21, in a conference room at a county title office. Ena brought her own silver pen, engraved with her initials and the words “48 years,” a retirement gift from the credit union where she had worked.
Her son, Landon, and his wife, Noel, were buying a $525,000 house in a subdivision called Cobble Run. They put down $125,000 and borrowed the remaining $400,000 at 6.75% over 30 years.
Landon earned $79,000 a year fixing heating and cooling systems. Noel had left her marketing job 19 months earlier to shoot weddings, and lenders want two years of tax returns before they count that kind of income. With Ena’s pension and Social Security added, the couple’s debt ratio dropped from about 60% to about 36%.
Ena signed the note but not the deed. That is exactly what a mortgage co-signer does: she carries the debt without owning the house. Her one request was a written promise from her son to refinance her off the loan within 24 months.
When the papers were done, Landon pressed a brass house key tied with red ribbon into her palm. Noel thanked her the way you thank a bank teller when you are already looking past her.
A Career Spent Reading the Margins
Ena started as a teller in 1973, at nineteen, owning two skirts. In 1993, her husband packed two duffel bags and left while she was at work. Her six-year-old son asked whether his father had left because of him, and she promised herself he would never have to ask her for anything twice.
She finished a finance degree at night in 1995, at 41. She rose to chief lending officer and retired in 2021 after 48 years and roughly 30,000 loan files.
People rarely lie on the lines, she learned. They lie in the margins. That habit made her an unusually careful mortgage co-signer, one who read every page before touching her pen.
Forty Invitations and No Place for a Mortgage Co-Signer
On Saturday morning, Ena arrived with a philodendron and a small red toolbox holding a level, picture hooks, and labels for the breaker panel. She knocked even though she had a key, because a key is permission but not an invitation.
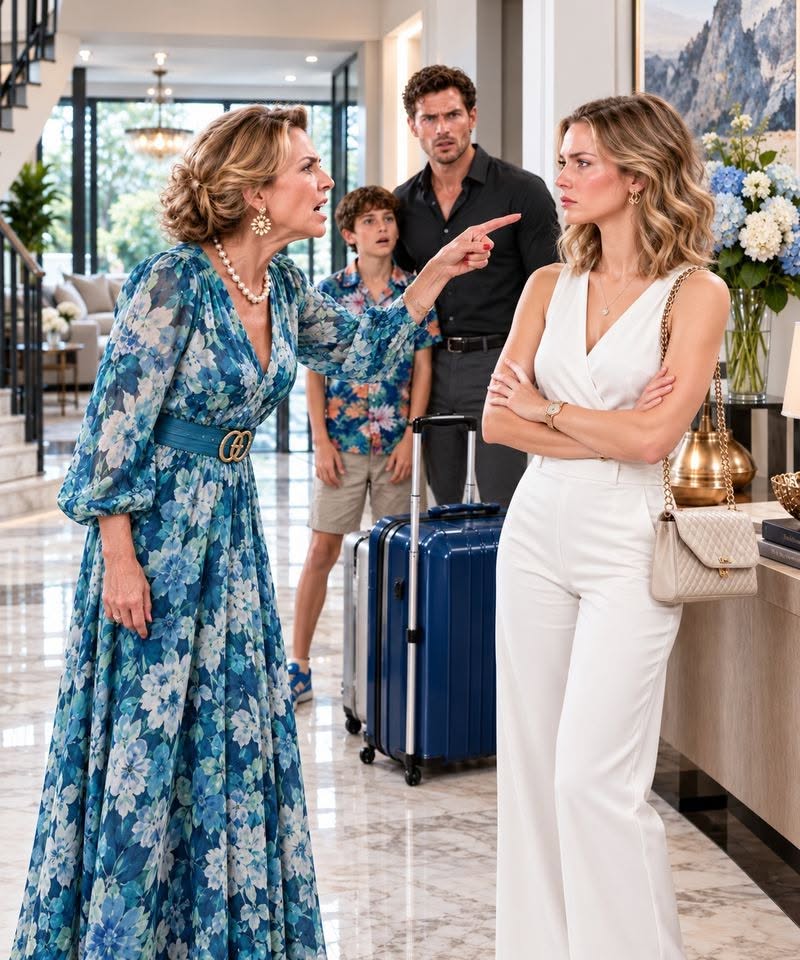
On the white quartz island sat a stack of cream envelopes stamped with gold foil keys, all addressed in Noel’s mother’s looping handwriting. Ena counted forty. The card on top invited guests to celebrate Landon and Noel’s new home on September 13, hosted by Daryl and Valerie Whitlo. None of the envelopes bore her name.
The next afternoon, she called her son and asked why. He answered plainly: “Her parents will be there. You don’t fit in.” Ena said she understood. She also understood whose sentence it was, because Landon had never once said “fit in.” His mother-in-law said it all the time.
Five Sentences From a Mortgage Co-Signer
Ena knew the rules better than most. A purchase loan has no undo button, and the three-day right to cancel covers certain refinances, not home purchases. A mortgage co-signer stays on the debt until it is paid off, refinanced, or the lender agrees to a replacement who qualifies.
On Monday, she called the loan officer, who explained that replacing her would require a refinance and about $8,900 in closing costs. Then she emailed Landon and Noel, copying the Whitlos. She offered to be replaced on the loan by Noel’s parents and to pay every dollar of the costs. Her last line stood alone: “Then let them sign.”
That evening, Landon called in a panic. Noel had gone white and gone to bed. Ena noticed something: a daughter who believes her parents are wealthy picks up the phone and tells them to call the lender. She does not go pale.
Valerie phoned the next morning, furious about being humiliated in writing. Daryl called a day later, smooth as a showroom floor, and blamed unspecified tax reasons. He never asked about the interest rate or the monthly payment. In 48 years, Ena had never met an honest borrower who failed to ask what the payment would be.
Why Daryl Resented the Credit Union
Six years earlier, Ena had chaired the committee that declined a $350,000 working-capital request from Daryl’s car dealership. She would not say why then, and she will not say now, because a member’s application belongs to the member.
Valerie came to the lobby afterward and begged her to reconsider, hand on her sleeve. Ena could only say she could not discuss it. The dealership closed in March 2020, and Daryl blamed the woman at the credit union ever since. He has not shaken her hand since.
Rumors, a Baby, and a Hidden Folder
On September 2, Landon texted that Noel was pregnant, due in February. Ena cried at the sink and bought a pale yellow baby blanket, which she tucked away in her hall closet to wait until someone asked for it.
On September 13, a neighbor named Railene Hulcom phoned after the party. Daryl had toasted “the house Val and I helped make possible,” and Valerie had told guests Ena tried to pull out of the mortgage. By Sunday, the rumor had reached Ena’s quilting group and her church. She corrected no one.
Soon after, Landon brought her a home equity application from another bank. It asked for $65,000 to “finish lower level” and left a co-applicant line blank for her name. Ena took it home to read. Behind the last page was a reinstatement quote for the Whitlos’ lake house, totaling $61,412.18 and good through October 24. A yellow note was stuck to it: “HELOC → Daddy. Wire by October 24th. Don’t tell L until it’s done.”
The math was careful. The new line would push the house to 88.6% of its value, just under the bank’s 90% limit. A mortgage co-signer’s name on that application would have quietly funded the rescue of a house that was heading to foreclosure.
Ena returned the folder to Noel the next morning. Noel warned that Ena would never meet the baby if she told Landon. Ena agreed to stay silent but gave Noel until Friday, because she wanted her son to choose on the truth, not on his mother’s word.
Then the local paper ran a legal notice for a sheriff’s sale of the Whitlos’ lake house, set for October 30. Public court records confirmed the foreclosure had been moving since February.
Lantern Night: A Mortgage Co-Signer Says No
Daryl invited Ena to lunch, asked for “one signature,” and slid an invitation across the table for Heron Point Lantern Night on Saturday, October 4. “Bring a pen,” he said. Ena did the math. A signature that night would put money in the bank right before the October 24 deadline.
She arrived to find 112 paper lanterns strung along the dock and 59 place cards on the welcome table. Hers sat at the last table, beside the bait shed. A retired county records clerk named Myron Sutton shook her hand and mentioned that he still read every legal notice on Thursdays.
Daryl raised his glass and thanked Ena for coming to “sign the papers that finish our kids’ home.” Valerie carried a green folder and a gold pen across the lawn and set them in front of her. Ena said four words at a normal volume: “I won’t be signing.”
She read her August letter aloud. Valerie shouted that they had bought the kids that house, and a friend answered that Valerie had told everyone she paid the down payment. Landon stood and said his mother had co-signed. The Whitlos had signed nothing.
Valerie screamed that Ena did not fit in. “That’s true,” Ena replied, and sat down.
Myron then asked Daryl whether the sheriff’s sale was for this house. Noel broke down and admitted the credit line was meant to cover her father’s debt, not a basement. Daryl flung his pen into the lake, but Ena still refused to explain why his loan had been declined.
Landon walked across the lawn and told Valerie, “You were right. She doesn’t fit in here. Neither do I.” He offered his mother his arm. At her car, he held out the brass key. “Ask me again when it isn’t an apology,” Ena said.
What Became of Everyone After Lantern Night
The home equity application was never filed. On October 30, the lake house sold for $371,000, enough to cover what the Whitlos owed. Today they rent a two-bedroom apartment for $1,250 a month, and Daryl sells cars on commission.
Noel stayed with her parents for eleven days, then came home. She and Landon see a counselor every Wednesday. The basement suite became a nursery, and their daughter arrived on a Tuesday in February, weighing seven pounds, two ounces. Noel let Ena hold her and said thank you, looking her in the eye.
A week later, Landon returned the key. “It’s yours, Mom,” he said. Ena keeps it in a kitchen drawer beside the silver pen and still knocks when she visits. The couple plans to refinance in June and pay their own closing costs.
Lessons From One Mortgage Co-Signer’s Story
Ena’s experience shows that a signature is a commitment, not a favor that can be taken back. Anyone thinking about becoming a mortgage co-signer should understand that the debt is real, the exit is difficult, and the deed may never carry their name.
The Consumer Financial Protection Bureau offers plain-language guidance on home loans and co-signing for families weighing these choices. For organizing closing documents, loan paperwork, and sample forms, you can also browse the resources at Sample PDF File.
Ena says she does not regret signing for her son and would do it again. What she learned is the difference between giving her name and giving herself away. Every mortgage co-signer deserves to be treated as family, not as a line item, and a signature should go only to people who would sign for you, too.